
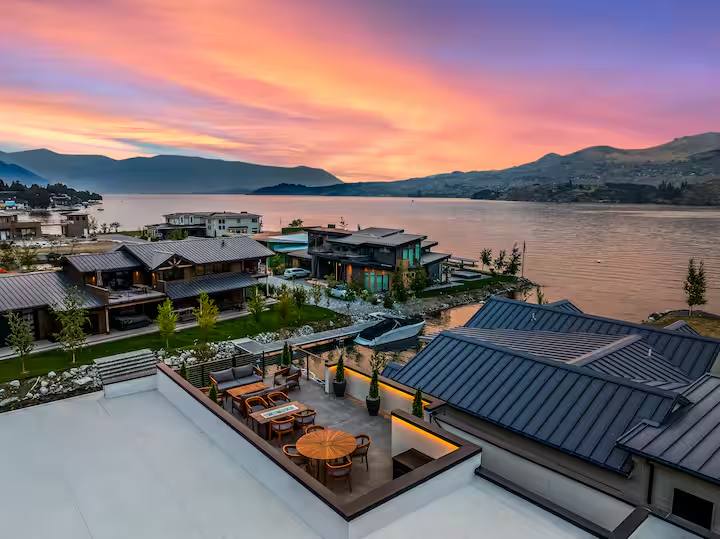
High-Balance DSCR · Short-Term Rentals
Financing for luxury short-term rentals.
Multi-million-dollar vacation rentals qualify on the income the property produces, not on your tax returns. Loan amounts to $5 million and above, with no published ceiling.
What's your goal?
Pick what you'd like to do — we'll customize from there.
Closed Deals
Three recent luxury short-term rental closings.
None of these properties had twelve months of short-term rental history to work from. Each one qualified on projected income — an appraiser's short-term rental analysis form or an AirDNA market report — and each borrower walked away with cash.
- Cash out
- $1M+
- Income used
- Appraiser STR analysis
- Structure
- Cash-out refinance
- Cash out
- $1,000,000
- Income used
- Appraiser STR analysis
- Closed in
- 35 days, two appraisals
- Cash out
- $500,000
- Income used
- AirDNA market report
- Structure
- Cash-out refinance
The $2.8 million file closed in 35 days, past our standard 14-30 day window, and that is the point. It carried two independent appraisals because of the loan amount. Sequencing them properly, rather than running one and then discovering a second was needed, is what kept the closing on schedule.
Closed transactions shown with identifying details removed. Past results do not guarantee future terms; every file is underwritten on its own merits.
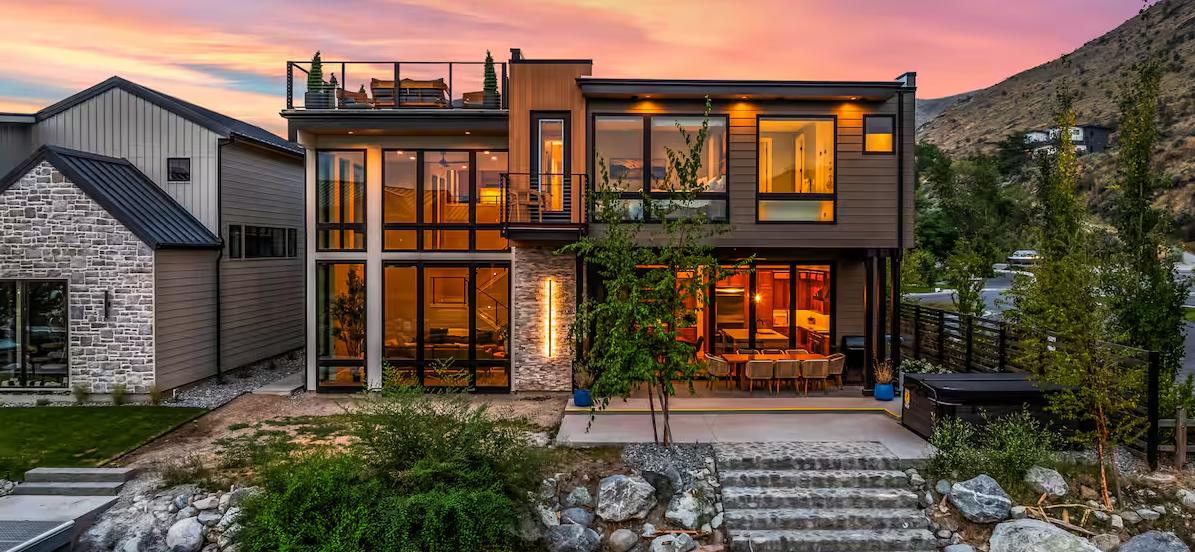
A short-term rental financed by Quicker Home Loans.
What We Finance
What makes a property a luxury short-term rental.
A luxury short-term rental is an investment property whose nightly rate is driven by proximity to a destination. It is rarely the finishes that set the rate. It is the beach, the ski lift, the golf course, the lake, the national park entrance, the wine region, the desert resort corridor, or the downtown event district the property sits next to.
We finance all of it: single family, condo, townhouse, and 2-4 unit, as long as the property is non-owner-occupied and held as an investment.
Qualifying Income
Three ways to document short-term rental income.
DSCR is gross rental income divided by PITIA. For a short-term rental, the only real question is where that income figure comes from. We accept three sources, and on a property with no rental history the second and third are what get the deal done.
Method 01
12-month rental history
Trailing twelve months of actual short-term rental income on the subject property. Platform earnings statements, host reports, or property-management income summaries from Airbnb, VRBO, Furnished Finder, or direct bookings.
Method 02
AirDNA market report
A market-data projection of what the property should produce as a short-term rental, built from comparable listings in its submarket. Used when the property has no operating history or has been owner-occupied.
Method 03
Appraiser STR analysis
A short-term rental analysis form completed as part of the appraisal. An independent appraiser's own opinion of short-term rental income for that address, which carries weight on high-balance files.
No tax returns and no personal debt-to-income calculation. DSCR uses gross rental income, so management fees and operating costs are not deducted from the qualifying figure.
STR DSCR Calculator
Run your nightly rate through the DSCR test.
A standard DSCR calculator asks for monthly rent. Short-term rentals do not work that way. This one takes your average daily rate and occupancy, converts them to monthly gross income, and divides by PITIA — the same math underwriting runs.
DSCR qualifies on the interest-only payment when IO is selected, which raises the ratio.
Estimated DSCR
1.19
Qualifies — standard program- Gross monthly STR income
- $18,782
- Gross annual STR income
- $225,388
- Principal & interest
- $12,972
- Taxes, insurance, HOA
- $2,750
- Total PITIA
- $15,722
Monthly cash flow before operating costs: $3,060
Get a real quote →Estimate only, not a quote or a commitment to lend. DSCR uses gross rental income; management fees and operating costs are not deducted from the qualifying figure. Actual DSCR depends on the appraisal, the documented income method, and full underwriting.
High-Balance Files
What changes above $1.5 million.
Most lenders publish one set of DSCR guidelines and let you discover the high-balance requirements during underwriting. Here is what actually shifts as the loan amount climbs.
Two appraisals at $2 million and above
Loan amounts of $2 million or more typically require two independent appraisals. Between $1.5 million and $2 million, the investor or underwriter may request a second appraisal depending on the property and the market. We tell you at quote, not at closing, so the extra time goes into your contract dates.
No published ceiling
Loan amounts run to $5 million and above. We do not publish a hard cap, because the limit is set by the property and the file rather than by a number on a rate sheet. Bring the scenario and you get an answer quickly rather than a full application first.
Appraisal quality drives the file
High-end vacation properties often carry thin comparable data, with few recent sales at the same price point and limited short-term rental comps. A strong appraisal with a well-supported STR analysis is usually the difference between a clean approval and a re-trade.
Cash-out proceeds can serve as reserves
Reserves typically run 3-12 months of PITIA in liquid assets. On a cash-out refinance, the proceeds themselves can often satisfy the requirement, which means no separate reserve funds are needed at closing. It depends on the scenario, so ask.
Entity vesting is the norm
Most luxury short-term rentals close in an LLC for liability protection, with no rate penalty for entity vesting. Corporation, trust, and personal-name vesting are also available.
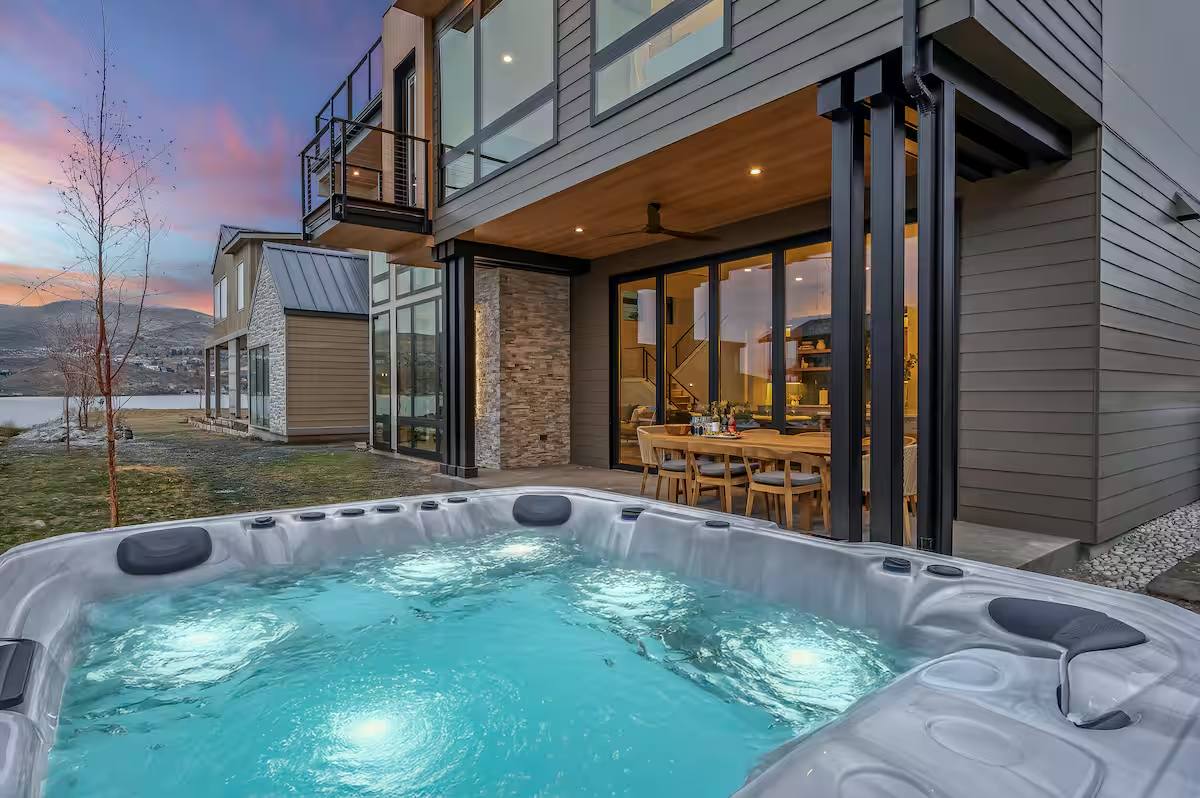
Amenity density drives nightly rate, and nightly rate drives DSCR.
Cash-Out Refinance
Pulling equity out of a luxury short-term rental.
Maximum LTV on a cash-out refinance is 75%. On many scenarios there is no hard dollar cap on the cash you take out. At more conservative leverage, in the range of 65% LTV, unlimited cash-out is frequently available. Some scenarios do carry a cap, often around $500,000, depending on the property, the market, and the strength of the file.
This is the most common reason high-balance short-term rental owners call us. A property that has appreciated and produces strong nightly income is usually sitting on significant trapped equity.
Seasoning works the same way. There is no single rule that applies to every file. Some scenarios allow a cash-out refinance at full appraised value with no seasoning period; others require the property to be held for a period first. It depends on how the property was acquired, what work has been done to it, and how the income is documented.
One practical advantage at this level: the cash-out proceeds can often serve as your reserves. Where that applies, there is no separate reserve requirement to fund at closing.
Program Details
Luxury short-term rental DSCR guidelines.
| Loan amounts | $5,000,000+ — no published cap; the file sets the limit, not a rate sheet |
| Loan floor | $100,000 (short-term rental is a specialty program) |
| Max LTV — purchase | 80% |
| Max LTV — cash-out | 75% |
| Minimum DSCR | 1.0 standard; Sub-1 and No-Ratio options available with an LTV reduction |
| Minimum credit score | 620 |
| Income documentation | 12-month STR history, AirDNA report, or appraiser STR analysis form |
| Platforms accepted | Airbnb, VRBO, Furnished Finder, direct booking, property-managed |
| Appraisals | Two typically required at $2M+; a second may be requested at $1.5M+ |
| Property types | SFR, condo, townhouse, 2-4 unit — non-owner-occupied |
| Vesting | LLC, corporation, trust, or personal name — no rate penalty for entity |
| Loan terms | 30-year fixed, 40-year, interest-only available |
| Reserves | Typically 3-12 months PITIA; cash-out proceeds can often satisfy the requirement |
| Prepayment penalty | 3-5 year stepdown, with a no-PPP option available |
| Closing timeline | 14-30 days; high-balance files with two appraisals run longer |
Pricing
What actually moves your rate.
DSCR pricing is driven by the file, not by a posted sheet. Five inputs do most of the work.
- Loan-to-value
- The single biggest lever. Lower leverage prices better and also opens up the unlimited cash-out scenarios.
- Credit score
- Pricing improves in tiers as the score rises. 620 is the floor on standard DSCR.
- DSCR ratio
- A property covering well above 1.0 prices better than one sitting right at the line.
- Loan amount
- High-balance files price differently than standard ones, in both directions depending on the rest of the file.
- Property location
- Market and ZIP code factor into both pricing and available leverage, particularly in seasonal and resort markets where comparable data is thinner.
Already holding a term sheet from another lender? Send it over and we will look at whether we can improve on it.
Questions
Luxury short-term rental financing questions
Yes. Quicker Home Loans writes short-term rental DSCR loans to $5 million and above, with no published ceiling. The limit is set by the property, the leverage, and the strength of the file rather than by a fixed cap. The property qualifies on its own short-term rental income, not on personal tax returns.
Business-purpose loans on non-owner-occupied investment property only. Quicker Home Loans LLC lends in 45 states. Program terms are guidelines, not commitments to lend; final terms depend on the property, the borrower, and the complete file.
Related: DSCR loans for Airbnb & short-term rentals · DSCR cash-out refinance · DSCR rental calculator
Trusted Lender
Connect with the right team to keep your transaction smooth from app to close.
Creative Solutions
Self-employed, foreign national, ITIN, mixed-use — we have a program for you.
Secure & Private
Your data is encrypted and never sold.
Fast to Close
Average 14–30 days from clean app to clear-to-close. Same-day scenario response.
Ready to lower your rate?
DSCR Loans — Lower Rates Are Here.
Cash Out Refinance — More cash flow. More properties.
Send us your scenario or upload a competing term sheet — we'll either beat it or tell you straight up that you've got a great deal.